

Bread Financial
4.7

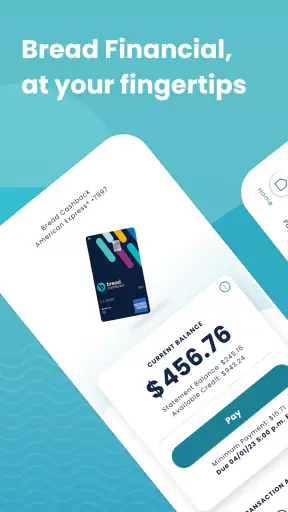
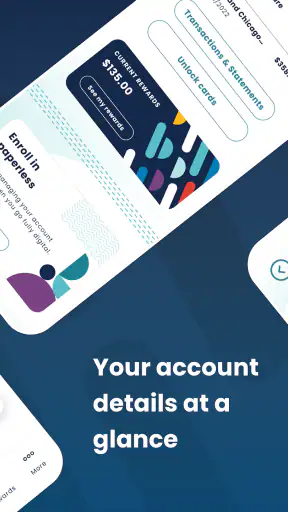
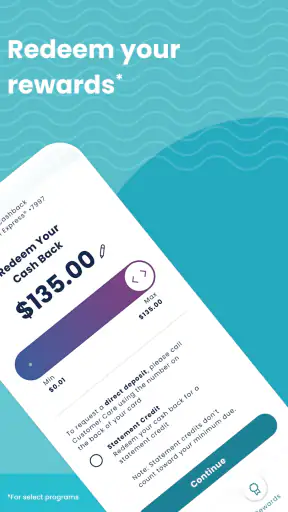
Managing a store account from a phone can be either pleasantly simple or unexpectedly frustrating, depending on how clearly the app presents the important actions. My first impression of Bread Financial is that it is built for a focused job: helping account holders check their account, make payments, and handle available rewards without needing to rely on a desktop browser. It is a free finance app from Bread Financial Holdings, Inc., and it is aimed at everyday account management rather than broad personal budgeting.
That distinction matters. I would not install this expecting a complete replacement for a banking app, an investment dashboard, or a detailed expense tracker. I see it as a companion for people who already use a qualifying Bread Financial account and want a more direct way to stay on top of it. When that is your situation, the app’s narrow purpose can be an advantage because the main tasks are easier to find than they often are inside a large, all-purpose financial service.
What to expect before you begin
The app sits in the finance category and is suitable for Everyone. It has reached over 500 thousand installs, with a 4.7 average from around 39 thousand ratings. Those figures suggest that the basic account-management experience works well for a substantial number of users, although a high store rating should not be mistaken for a guarantee that every account or every device will behave identically.
On my first visit, I would approach it with one question: “What do I need to do today?” If the answer is checking an account, making a payment, or redeeming rewards, the app is relevant. If the answer is combining several bank accounts, categorizing spending, setting a household budget, or monitoring investments, I would choose a broader financial tool instead. Bread Financial is more specialized than that.
The current version is 5.8.2, and the app requires iOS or Android version 11 or later. That operating-system requirement is worth checking before downloading, especially if you keep an older phone as a backup. The app itself is free, but “free” here describes the download, not the financial terms of the account you access through it. I would still read the terms connected to your account and payment arrangements rather than assuming the app changes them.
A useful way to think about the experience is as a secure control panel for an existing relationship. The app is not where I would expect to discover a new financial product or build a long-term money plan from scratch. Its value begins once I have an account to manage and a specific task in mind.
Who will get the most from it
I think this app is best for someone who wants a quick, phone-based routine. Perhaps you receive a reminder that a payment is due, want to confirm the account before making a purchase, or have rewards available and do not want to open a laptop. Those are small moments, but removing extra steps can make it more likely that the task actually gets completed on time.
It is also useful for people who prefer separating account servicing from general money management. I like that approach because a specialized app can keep the important account actions together instead of burying them among unrelated charts and categories. On the other hand, users who want one screen for all their financial institutions may find the narrower scope limiting.
Who should choose another type of app
I would skip this as my main finance app if I wanted a complete picture of income, bills, savings, credit cards from different providers, and investments. A general banking app or budgeting service would be a better fit for that job. Bread Financial is not a substitute for every financial tool simply because it handles payments and rewards.
I would also be cautious if my main need is detailed historical analysis. The most useful experience here is action-oriented: check the account, complete a payment, or use rewards. Someone who enjoys building reports and comparing spending categories may find a dedicated budgeting application more comfortable.
Getting from installation to a useful first session
Start with the account details you actually need
Before opening the app, I would have the relevant account information available and make sure I am using the details associated with the Bread Financial account I intend to manage. This sounds obvious, but it prevents the most common first-session problem: trying to register or sign in while switching between several email addresses or accounts.
I would also avoid rushing through the opening screens. In a finance app, the fastest path is not always the safest path. I want to confirm that I am entering the correct account, review each screen carefully, and pause if something does not match what I expect. A few extra seconds at setup are preferable to beginning a payment workflow with the wrong account context.
The developer is Bread Financial Holdings, Inc., which is useful to recognize when checking that I have installed the intended application. I would look at the app name and developer together rather than relying only on a familiar icon. That simple habit is especially worthwhile with financial applications, where similarly named services can cause needless confusion.
Make the first meaningful action deliberately
For a first successful session, I would choose one modest task rather than trying to explore everything. Checking the account is a sensible starting point because it lets me confirm that the correct account is visible and that the information looks familiar. Once that feels right, I would move to the action I actually came for.
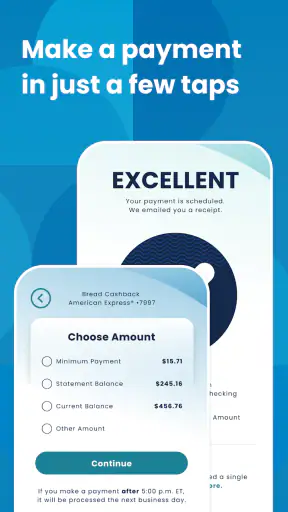
If I needed to make a payment, I would treat the process like a checklist. I would verify the account, review the amount, inspect the payment details before submitting, and keep the confirmation screen or message available until I am satisfied that the action went through. I would not close the app immediately after tapping a button simply because the screen changed. In financial workflows, the final confirmation matters more than the tap itself.
For rewards, I would first identify what is available and then read the redemption choices carefully before committing. Rewards are easy to treat as “free money,” but their usefulness depends on how and when they can be applied to the account. I prefer to decide what I want the reward to accomplish—reduce an amount due, use it toward a purchase, or simply save it for later—before selecting an option.
My practical tip is to use the first session as a verification session, not just a login session. Confirm the account identity, locate the payment area, find the rewards area, and learn where confirmation information appears. That small orientation exercise makes later visits much calmer, particularly when I am using the app while distracted or away from home.
A realistic everyday scenario
Imagine I am about to leave for work and remember that I have not dealt with an upcoming account payment. Instead of waiting until I have access to a computer, I open Bread Financial, check that I am viewing the intended account, and go directly to the payment task. I review the amount and details, submit it, and make sure the app shows a completed confirmation before putting my phone away.
Later, I might return to check whether rewards are available. I would not combine that with the payment decision unless I had enough time to read the redemption information. Separating those two tasks reduces the chance of tapping through a reward choice without understanding it. The app is most helpful in this scenario because it shortens the route from reminder to completed action.
Where first-time users may hesitate
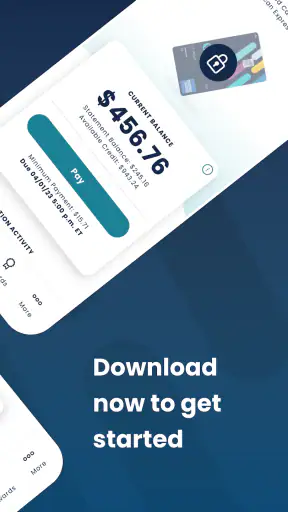
The main source of uncertainty is usually not the button itself but the meaning of the account information around it. A balance, payment amount, available rewards, and confirmation status can serve different purposes. I would read the labels rather than assuming the largest number on the screen is the amount I need to pay.
Another point of friction is the difference between starting a payment and knowing that it has been accepted. I would look for the app’s final acknowledgement and keep any reference information shown there. If I am unsure whether an action completed, I would avoid submitting the same payment repeatedly until I have checked the account status or the relevant confirmation details.
Rewards can create a similar hesitation. Seeing a reward available does not automatically mean every redemption option is equally useful. I would compare the choices presented in the app with my immediate goal. If I am trying to reduce what I owe, I would focus on options that support that purpose; if I am saving rewards for a later purchase, I would avoid redeeming them impulsively.
How it compares with familiar alternatives
Compared with a traditional desktop account portal, the app is more convenient for short, time-sensitive tasks. I can reach the account while commuting, waiting in line, or sitting at the kitchen table with only my phone. The trade-off is that a smaller screen may make detailed review less comfortable, especially when I want to inspect several pieces of information at once.
Compared with a general banking app, Bread Financial should feel more focused but less comprehensive. A bank app may bring checking, savings, transfers, deposits, and other services into one place. This app’s strength is concentration on the Bread Financial account experience, not acting as a universal financial hub.
Compared with a budgeting app, the difference is even clearer. Budgeting tools help me understand patterns across spending and plan future money decisions. Bread Financial helps me act on a particular account. I would happily use both if I needed both jobs: one for planning, the other for servicing the account and handling rewards.
Small habits that make the app more useful
I would keep notifications or reminders, where available through my device and account setup, tied to a routine rather than checking randomly. For example, I might review the account when I receive a payment reminder, then complete the task in the same session. This keeps the app connected to a real decision instead of turning it into another icon I forget.
I would also avoid using the rewards section only when I am ready to spend. Checking it during a calm moment helps me understand what is available before I am standing at a checkout. That is a non-obvious advantage of having the account on a phone: I can separate learning about the reward from the pressure of making a purchase.
Finally, I would review the app after an update rather than assuming every screen is exactly where I remember it. Version 5.8.2 is the current version, and app interfaces can evolve. A quick look at the payment and rewards paths after updating can prevent mistakes caused by relying on an old mental map.
Security-minded use without unnecessary anxiety
I treat any finance app as a place for deliberate phone habits. I would use my own device, keep the operating system supported, and avoid entering account details while connected to an unfamiliar network if I can wait. I would also lock the phone and avoid leaving a confirmation screen visible when someone else could read it.
These are not reasons to avoid the app. They are simply sensible boundaries. The convenience of completing a payment from a phone is valuable, but convenience should not turn into careless tapping. I especially recommend checking the account name and amount immediately before submission, because that is the point where a quick review has the most practical value.
My final view after using it
I see Bread Financial as a useful, specialized finance app for existing account holders who want a straightforward mobile route to account checks, payments, and rewards. Its strongest quality is focus. I do not have to open a full banking ecosystem when the task in front of me is limited to this particular account.
That focus also defines its limits. It is not the right choice for someone searching for a complete budget planner, a multi-bank dashboard, or an investment tool. Those users should pair it with, or choose instead, a service designed for broader financial planning. The app makes more sense as one precise instrument rather than an entire financial toolbox.
For a first-time user, my recommendation is simple: install it only if you have a Bread Financial account to manage, begin by confirming the correct account, and complete one small task carefully. Once you know where payments and rewards live, later sessions should feel much more direct. I would recommend it to a friend who wants mobile account servicing without unnecessary extras, while reminding them to read payment and redemption details instead of treating every screen as self-explanatory.
In the end, the app succeeds when it helps me finish a real task with less friction: checking before a purchase, making a payment during a busy day, or using rewards at a sensible moment. That is a modest promise, but for the right user, it is exactly the kind of convenience a dedicated account app should provide.
4.7
3.12K Reviews
Pros
- Convenient access to account balances
- payments
- and transaction history.
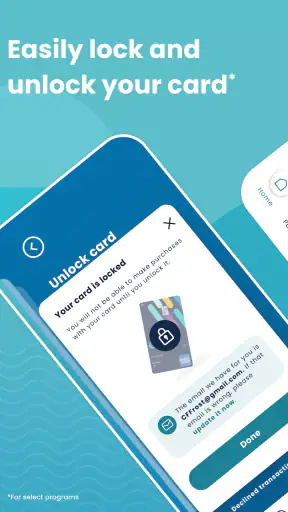
- Card alerts can help users monitor spending and spot unusual activity quickly.
- Digital statements reduce paper clutter and are easy to access when needed.
- Payment scheduling helps avoid missed due dates and potential late fees.
- The app supports secure sign-in options on compatible mobile devices.
Cons
- Features may vary depending on the specific Bread Financial account or card.
- Some users may experience delays when balances or payments are updated.
- Customer support options may be less convenient than in-app account tools.
- A mobile app cannot replace all services available through the full website.
- Credit products may include fees or interest charges that require careful review.


